Bought Something That Never Arrived? How to Use Chargeback to Get Your Money Back
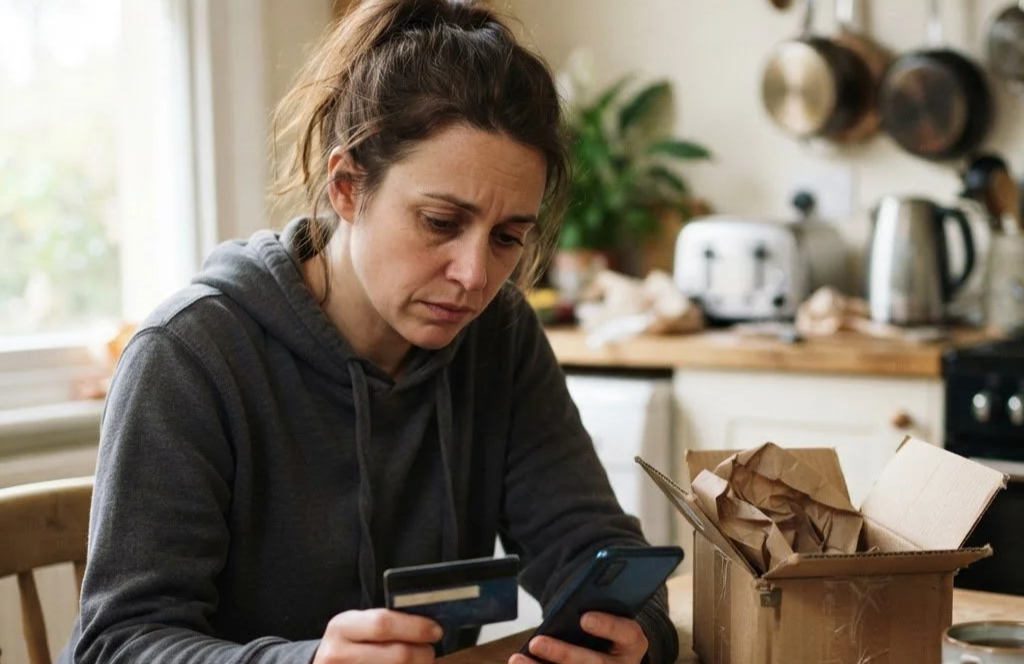
There is nothing more frustrating than eagerly awaiting a parcel that never arrives. Whether it is a birthday gift, a household essential, or a treat for yourself, the disappointment of a missing delivery is compounded by the stress of wondering if your money is gone for good. At Citizens Advice Lancashire West, we frequently hear from consumers who feel helpless after a retailer fails to deliver. However, if you paid by card, you may have a powerful tool at your disposal: the chargeback scheme.
Many shoppers are unaware that their bank can often help recover funds when a transaction goes wrong. While it is always best to contact the retailer first to resolve the issue, knowing your rights regarding card payments ensures you are not left out of pocket when things go awry.
What is Chargeback and How Does It Work?
The chargeback scheme is a set of rules established by card providers like Visa, Mastercard, and American Express. It is not a legal right in the same way as some other consumer protections, but rather a voluntary agreement that participating banks sign up to. Essentially, it allows your bank to reverse a transaction by reclaiming the money from the retailer’s bank.
You can typically use this process for problems such as:
Non-delivery of goods or services.
Faulty or damaged items.
A company going into administration before providing your order.
Because this is a card-scheme rule, it applies to a wide range of payments, including those made via debit cards, credit cards, and prepaid cards.
Chargeback vs. Section 75: What is the Difference?
It is common to confuse chargeback with Section 75 of the Consumer Credit Act 1974. While both offer protection, they operate differently. Section 75 is a legal right that makes your credit card provider jointly liable with the retailer for purchases between £100 and £30,000. It is a robust, statutory protection.
In contrast, chargeback is a broader safety net. It has no minimum or maximum transaction value, making it the primary route for debit card users or those who spent £100 or less on a credit card. If you are unsure which to use, always speak to your bank; they are obligated to guide you toward the most appropriate protection for your specific situation.
How to Start Your Claim
Before contacting your bank, you must attempt to resolve the issue directly with the retailer. Keep a record of all correspondence, including emails, order numbers, and any delivery tracking information. If the retailer is unresponsive or refuses to refund you, follow these steps:
Contact your bank: Inform them that you wish to initiate a chargeback claim for a non-delivered item.
Gather evidence: Provide your purchase receipt, proof of the expected delivery date, and evidence of your failed attempts to contact the seller.
Mind the clock: Most card schemes have a time limit for claims, typically 120 days from the date of the transaction or the expected delivery date. Do not delay.
When to Seek Further Advice
If your claim is unsuccessful, you may be able to escalate the matter to the Financial Ombudsman Service (FOS). This is a free, independent service that settles disputes between consumers and financial businesses. Their decision is binding on the bank, providing a final layer of security for your finances.
At Citizens Advice Lancashire West, we are here to support you. If you are struggling with a consumer issue or need help navigating the claims process, please reach out to our team. We provide free, impartial, and confidential advice to help you understand your rights and take the next steps with confidence.